Cross border guidance for Canadians living in the U.S.
Financial planning for Canadians building a new life in the United States, from an advisor who made the same move and still keeps one foot in both financial systems.
Moving from Canada to the United States opens up a new chapter, and along with it, a set of financial questions most people never had to ask north of the border. Retirement accounts, investments, real estate, taxes, estate plans, and insurance can all work differently depending on which side of the border you’re standing on. A decision that made perfect sense in Canada doesn’t always translate once you’re a U.S. resident, and by the time most families realize that, they’re already several decisions in.
For Kris Maxwell, this isn’t just a specialty. It’s something he’s lived. Kris and his family went through the immigration process themselves, built a new life in the United States, and kept managing real estate, investment accounts, and financial relationships back in Canada the whole time. That experience sits alongside nearly two decades in the Canadian investment industry and his current work as a CERTIFIED FINANCIAL PLANNER™ professional in the U.S. When Kris talks about what it’s like to have a financial life that spans two countries, he’s speaking from the inside of it, not just from training.
We help Canadians who’ve relocated permanently to the United States by providing general educational information regarding Canadian-issued policies. We are not licensed to provide advice regarding Canadian-issued insurance policies or investments where a Canadian license is required. Any Canadian-specific recommendations must be made by appropriately licensed Canadian professionals. We help coordinate reviews with appropriately licensed Canadian professionals.
What crossing the border actually changes
U.S. financial and investment planning
Once you’re a U.S. resident, your financial plan needs to be built around U.S. rules from the ground up, not adapted from a Canadian one. That means investment accounts, tax strategy, and retirement planning designed for the system you actually live under now.
What’s still in Canada
Many people who move don’t fully exit Canada financially, and they don’t need to. RRSPs, Canadian brokerage accounts, and other assets left behind still need to be accounted for as part of the whole picture, not managed as an afterthought separate from everything else.
Important TFSA considerations
A Tax-Free Savings Account is exactly what it sounds like in Canada. It is not tax-free once you’re a U.S. resident, and it can create reporting complications many people never see coming until it’s already an issue. This is one of the first things worth reviewing after a move, not one of the last.
CPP, OAS, and Canadian pensions
These benefits don’t disappear when you relocate, and they shouldn’t be planned around as if they don’t exist. They need a place in a U.S. retirement income strategy, factored in alongside everything else you’re building here.
Real estate you still own in Canada
Keeping a home, a cottage, or an investment property in Canada after moving is common, and it comes with tax and legal considerations on both sides of the border. We help clients think through those decisions in coordination with the right Canadian professionals, rather than in isolation.
Currency and cross-border retirement income
Income that originates in Canadian dollars and supports a life priced in U.S. dollars adds a layer most domestic financial plans never have to account for. Currency exposure and timing become part of the retirement income conversation, not a detail to sort out later.
Estate planning, insurance, and beneficiaries
Wills, beneficiary designations, and insurance policies drafted under Canadian assumptions don’t automatically hold up the same way under U.S. residency. These get reviewed as part of the plan, not left as they were the day you crossed the border.
I am not licensed to service or provide insurance advice regarding Canadian-issued insurance policies where Canadian licensure is required. For Canadian residents or owners of Canadian-issued policies, I can provide general educational information and/or coordinate with appropriately licensed Canadian professionals. Any policy-specific recommendations regarding a Canadian-issued policy can be made only by professionals duly licensed in Canada.
One coordinated team, not two separate ones
The families who navigate this well aren’t the ones who pick a U.S. team or a Canadian team. They’re the ones whose U.S. and Canadian professionals, accountants, attorneys, and advisors, are actually talking to each other. That coordination is a core part of what we do.
Ongoing management, not a one-time fix
A cross-border financial life doesn’t get solved once and left alone. It gets managed continuously, as tax law, currency, and personal circumstances shift on both sides of the border.
Information regarding Canadian insurance products and investments is provided for educational purposes only and is not intended as insurance, investment, legal, or tax advice. Any Canadian-specific recommendations must be provided by appropriately licensed Canadian professionals. Individuals should consult their own tax, legal, and other qualified professionals regarding their specific circumstances.
A trusted U.S. partner for your clients
When a client moves permanently to the United States, Canadian licensing and regulatory requirements can limit how much a Canadian advisor is able to continue doing for them. We can step in as that client’s U.S. wealth management partner, working alongside the Canadian advisor and other professionals already involved rather than replacing them.
For Canadian firms, that means a trusted referral relationship and real continuity for a client going through a major transition. The goal isn’t to unnecessarily disrupt a relationship your client values. It’s to build a coordinated approach that reflects their new U.S. residency while still respecting the relationships and assets they maintain in Canada.
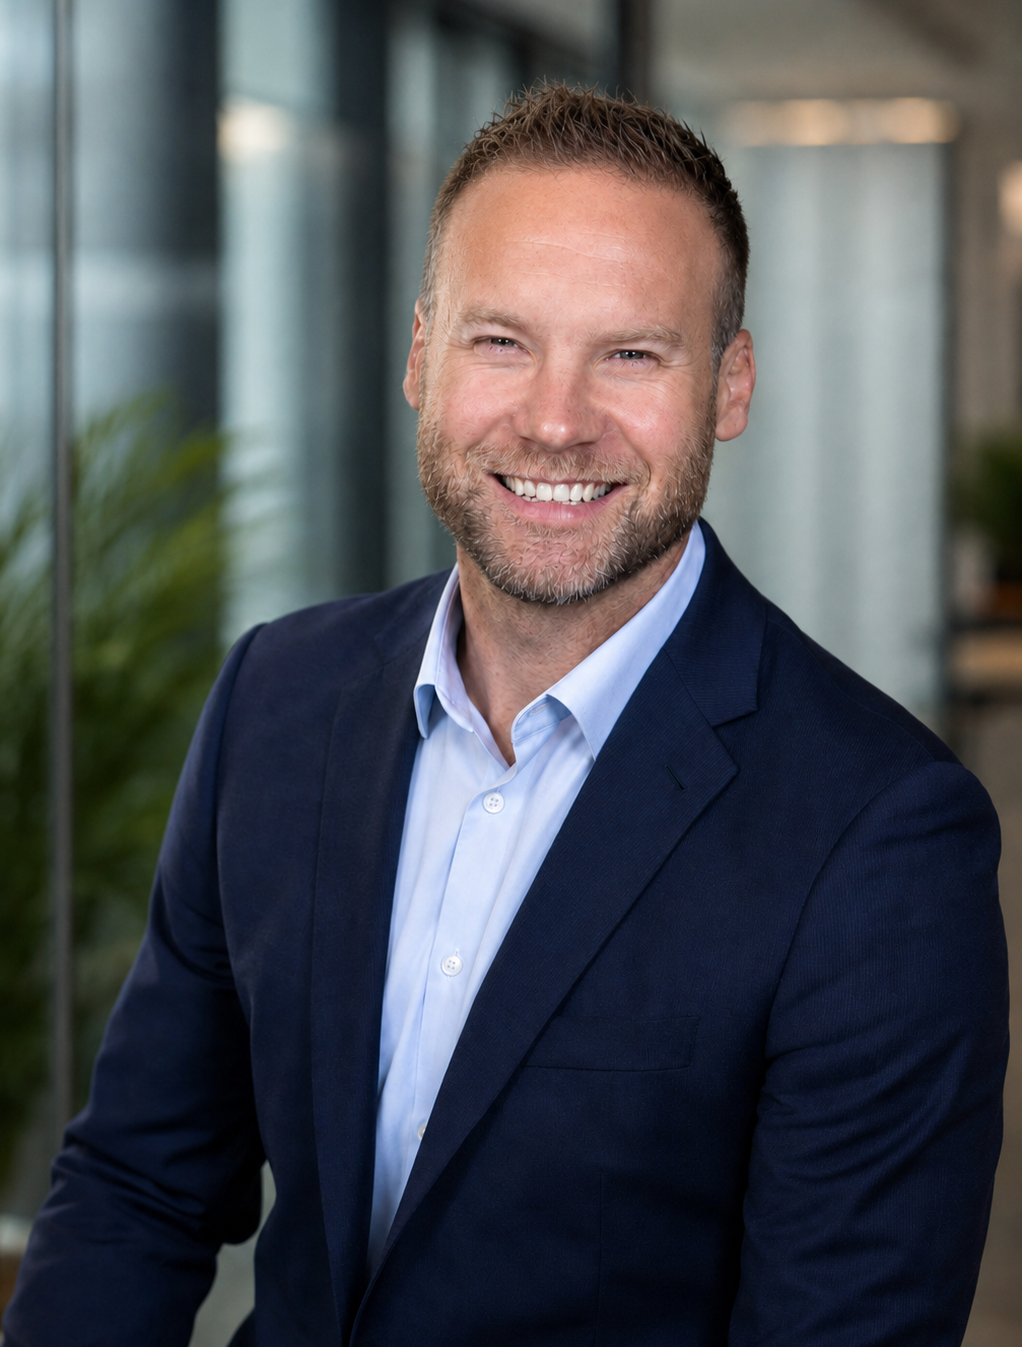
Kris Maxwell, CFP®
Partner | Financial Advisor
Kris Maxwell brings more than two decades of financial-services experience to his role as a Partner at VINITY Private Client Group. After beginning his career in banking, he joined Fidelity Investments before moving to TD Asset Management in Vancouver. As a Regional Vice President, Kris worked closely with financial advisors on portfolio construction, practice management, and enhancing the client experience. He also developed lasting relationships with portfolio-management teams across a broad range of investment disciplines.
This experience gave Kris a unique perspective on the financial-services industry and shaped his belief that effective planning starts with understanding each client’s goals, priorities, and vision for the future.
Kris earned a Bachelor of Business Administration with concentrations in finance and accounting from the University of New Brunswick. He later earned his CFP® certification and education through the Boston Institute of Finance at Bryant University.
After purchasing a home in Gilbert in 2011, Kris and his family developed a lasting connection to the desert and eventually made the community their permanent home. Outside the office, he coaches youth basketball, serves on his HOA board, and has twice completed the Vancouver-to-Seattle Ride to Conquer Cancer. He enjoys boating, skiing, fitness, traveling, exploring new places, and spending time with his wife and two children.
the invitation
Build a plan that actually follows you
Your move may have taken you across the border, but your financial life doesn’t automatically follow. Work with someone who understands the journey personally and professionally. Together, we can build a coordinated strategy for your life in the United States while accounting for the assets, relationships, and financial decisions you still have in Canada.